Starting a new business is exciting, and finding money to grow it is a big part of that journey. Many founders dream of getting enough start-up capital to make their ideas a reality. But here’s a secret: getting money, or fundraising, is not just about having a great idea or a strong business plan. It’s also about truly understanding the people who give out the money.
This means knowing how fund companies work. Funds, like venture capital firms, have their own rules, goals, and ways of doing things. If you don’t understand these, you might find it hard to get the money you need, or you might make deals that are not good for your company in the long run. For instance, knowing how funds plan for their own exits and returns can change how you negotiate your own deal terms. You should always model different scenarios for any deal you are offered to see how it affects your company over time, even beyond the current round of working capital funding 2026. This careful planning helps make sure you keep enough ownership and control for future growth. In fact, experts say it’s important to think about how your company’s ownership changes across different funding rounds, modeling at least three scenarios before you agree to anything 2026, including more founder-friendly and investor-friendly options to compare against the proposed deal 2026. This helps you see the bigger picture clearly, ensuring the deal makes sense for your future.
This guide is here to help you. We will explain the basic ideas of how funds work in simple terms.
You will learn about their goals, their structures, and how they think about time. We will give you simple, useful tactics you can use to help you raise money more easily. By the end, you’ll feel more confident when talking to investors and making decisions about your company’s future.
Staying informed about the wider tech world is also key for founders. It helps you see new trends and understand how they might affect your business and funding.
Get clear daily AI updates from The AI Newsletter Worth Reading.
To really understand how fund companies work, it helps to know about the two main groups of people involved: Limited Partners (LPs) and General Partners (GPs).
Think of them as the money givers and the money managers.
LPs, GPs, and Why Fund Structure Changes Founder Outcomes
Limited Partners (LPs) are the people or groups who put most of the money into a fund. These can be big organizations like pension funds, university savings, or even very wealthy families. They give their money to the fund, hoping it will grow over time. LPs usually don’t get involved in the daily decisions about which companies to invest in. They are "limited" because their risk is only as much as the money they put in. They want a good return on their start-up capital.
General Partners (GPs) are the people who run the fund. They are the ones who decide which companies get invested in, how much money each company receives, and how to help those companies grow. GPs manage the money from LPs and try to make it grow even more. When a company they invested in does very well, the GPs get a share of the profits, which is called "carry," on top of their management fees. This gives them a strong reason to find and grow successful businesses. This is a crucial part of knowing how fund managers think.
Their goals are usually the same: make money. But the way they go about it can affect founders. GPs are always looking for big wins because they need to show their LPs good returns to raise more funds in the future. This means they often push for deals that give them a good chance at a large profit, even if it means more dilution for founders. For example, founders are often advised to aim for giving up only about 15-20% of their company in a seed round to avoid problems in future funding rounds, so knowing this helps you negotiate better terms.
Common Fund Terms and Why They Matter
When you are looking for working capital funding, it’s good to know some key terms about funds:
- Fund Size: This is the total amount of money a fund has to invest. A bigger fund might make larger investments or invest in more companies. Understanding the fund size helps you guess if your company’s funding needs fit what they usually offer.
- Vintage Year: This is the year the fund started. It’s like the birth year of the fund. This year is important because it tells you how much time the fund has left in its "life."
- Investment Period: This is the time during which a fund actively looks for and makes new investments. It usually lasts about 3 to 5 years from the vintage year. If a fund is near the end of its investment period, it might be more eager to make deals or, sometimes, more selective if they have little money left.
- Fund Life: Most funds have a life of about 10 to 12 years. By the end of this period, the GPs need to have sold their investments and returned the money (and profits) to their LPs. This deadline means GPs are always thinking about when and how they will exit their investments, which can affect the timing of your company’s growth and eventual sale.
Knowing these things about how fund structures operate helps you understand the investor’s side better. It can help you figure out which funds are a good fit for your company and how to talk about your company’s future in a way that aligns with their goals. Being prepared means you can ask for better terms and protect your ownership as you grow your business. Many founders aim to give up only 15% to 25% of their company in each funding round, especially for seed and Series A. This shows why careful modeling of your ownership is so important before you make a deal. Experts agree that you should model dilution before every raise to know your ownership after the round. For example, try to keep pre-seed dilution capped at 20% to avoid problems in later rounds, according to one guide for Cap Table 2026 Examples: Pre-Seed to Series A Dilution.
Knowing the structure of a fund helps, but understanding how they make and share money is even more important for founders. This part looks at the main ways funds earn money and how these affect you.
Management Fees
First, let’s talk about management fees. These are fees that General Partners (GPs) charge the Limited Partners (LPs) to run the fund. Think of it like a salary for managing the money. This fee is usually a percentage of the total money in the fund each year. For example, a common fee might be 2% of the fund’s total capital. So, if a fund has $100 million, the GPs get $2 million a year to cover their team’s salaries, office rent, travel, and other costs of finding and managing investments.
These fees ensure the fund can operate, but they also mean GPs need to invest wisely. They must show good results to keep attracting capital wholesale and ensure their LPs continue to commit money to future funds. Because of this, GPs are always on the lookout for promising businesses that can offer strong returns.
Carried Interest (Carry)
Next is carried interest, often just called "carry." This is how GPs make their big profits. Carry is a share of the profits from successful investments. Once the LPs get back all the money they put into the fund, plus a certain minimum return, the GPs then get a percentage of the remaining profits. This split is often 20% for the GPs and 80% for the LPs. So, if a company the fund invested in sells for a lot of money, and the LPs have already gotten their initial investment back, the GPs take 20% of the extra profit. This system is a huge motivator for GPs to pick winners and help them grow as much as possible. It ensures that the interests of the GPs are aligned with the success of the companies they invest in, aiming for big exits that benefit everyone. This is a standard part of how fund managers negotiate terms, as detailed in guides on negotiating private equity fund terms.
Hurdle Rates
Sometimes, funds have a "hurdle rate." This is a minimum return that the LPs must achieve before the GPs can start taking their carried interest. For example, a hurdle rate might be 8%. This means the fund’s investments must return at least 8% to the LPs each year before the GPs get their 20% share of profits. This acts as another safeguard for LPs and keeps GPs focused on achieving solid returns.
Fund Life Stages and What They Mean for Founders
We talked about fund life before, usually 10 to 12 years. This period is split into a few stages:
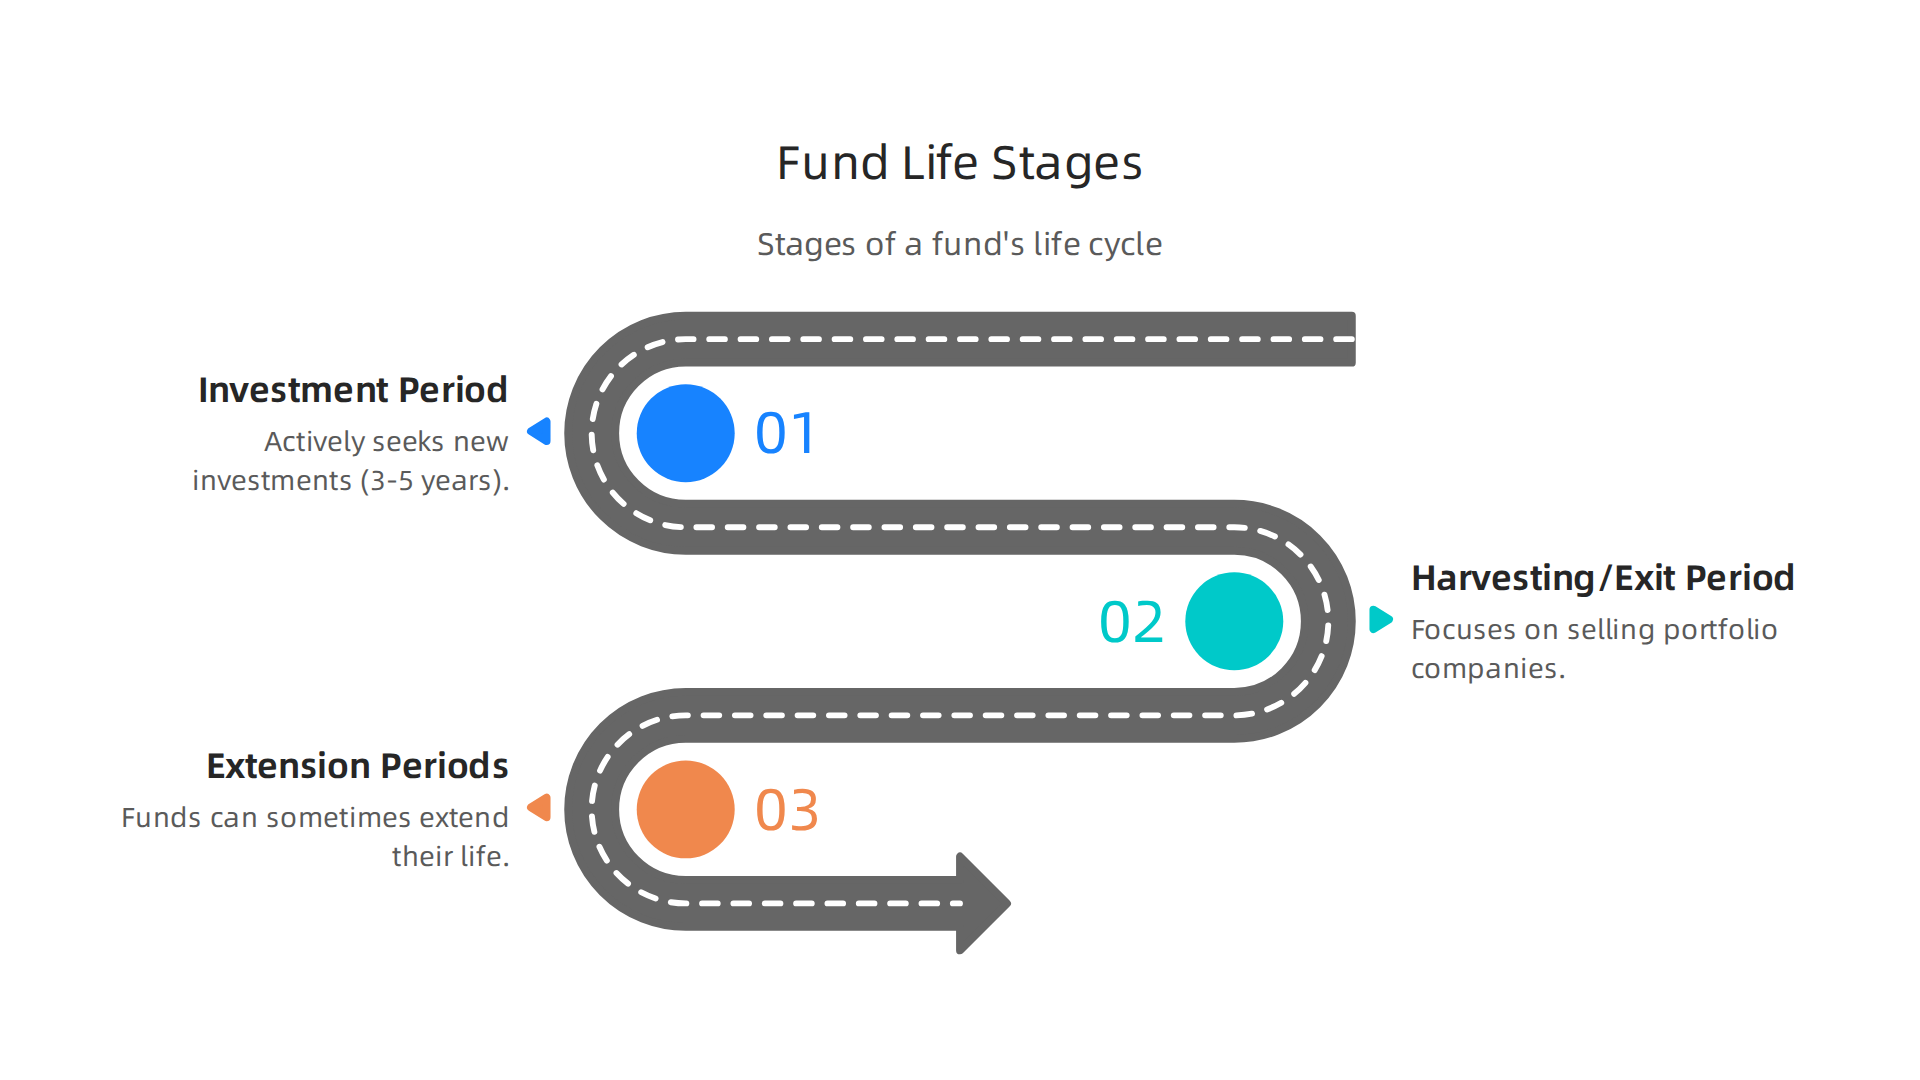
- Investment Period: This is when the fund actively seeks new investments, typically the first 3 to 5 years. If a fund is near the end of this period, they might be more eager to deploy any remaining capital or become more selective. Understanding this timing can affect your fundraising strategy and how fund managers view your pitch.
- Harvesting/Exit Period: After the investment period, the fund focuses on helping its portfolio companies grow and eventually selling them. This is when GPs are looking for "exits" through sales, mergers, or public listings. The fund’s deadline means GPs are always thinking about how and when they will exit their investments, which can put pressure on your company to meet certain growth targets and prepare for a sale. Documents like the LPA Template for VC: Key Clauses & 2026 Playbook often outline these terms.
- Extension Periods: Funds can sometimes extend their life, usually in one-year increments, but there are limits to how long this can go on, as highlighted in Private Equity Governance Best Practices. This can give companies more time to mature, but it also signals that the fund might be struggling to find good exits.
How Fund Economics Impact Founders
All these economic terms directly affect you, the founder.
- Term-Sheet Pressure: GPs want to get good returns for their LPs to justify their management fees and earn carried interest. This often means they will push for terms in your funding agreement that give them more control or a bigger share of future profits. This can lead to more dilution for you, meaning you own less of your company.
- Exit Expectations: Because of fund life limits and the desire for carry, GPs often have clear ideas about when and how your company should be sold. This can mean pressure to grow quickly or pursue a certain type of exit, even if it’s not exactly what you had planned. Knowing this helps you understand their timeline and plan your business growth accordingly.
- Governance: GPs will often take a board seat or have special rights to guide your company toward a successful exit. This affects how your company is managed and important decisions are made.
Understanding these details of how fund structures and economics work helps you protect your ownership and make smart decisions. It’s not just about getting working capital funding; it’s about partnering with investors whose goals align with yours for the long run.
To stay on top of daily insights into AI and technology, which can inform your startup’s strategy and help you attract the right investors, consider signing up for The AI Newsletter Worth Reading.
Understanding how funds make money and the different stages of their life helps you know what they expect. But how do funds decide which startups to put their money into? This involves a close look at your company through a process called "due diligence."
It also means looking at the specific rules written in the "term sheet" that comes with their offer.
How Funds Evaluate Startups: Due Diligence and Term-Sheet Priorities
When a fund thinks about giving you start-up capital, they do a deep dive into your business. This careful checking is called due diligence. It helps them see the good parts and the risky parts before they invest. Funds usually check a few key areas to see how fund-worthy your company is in 2026.
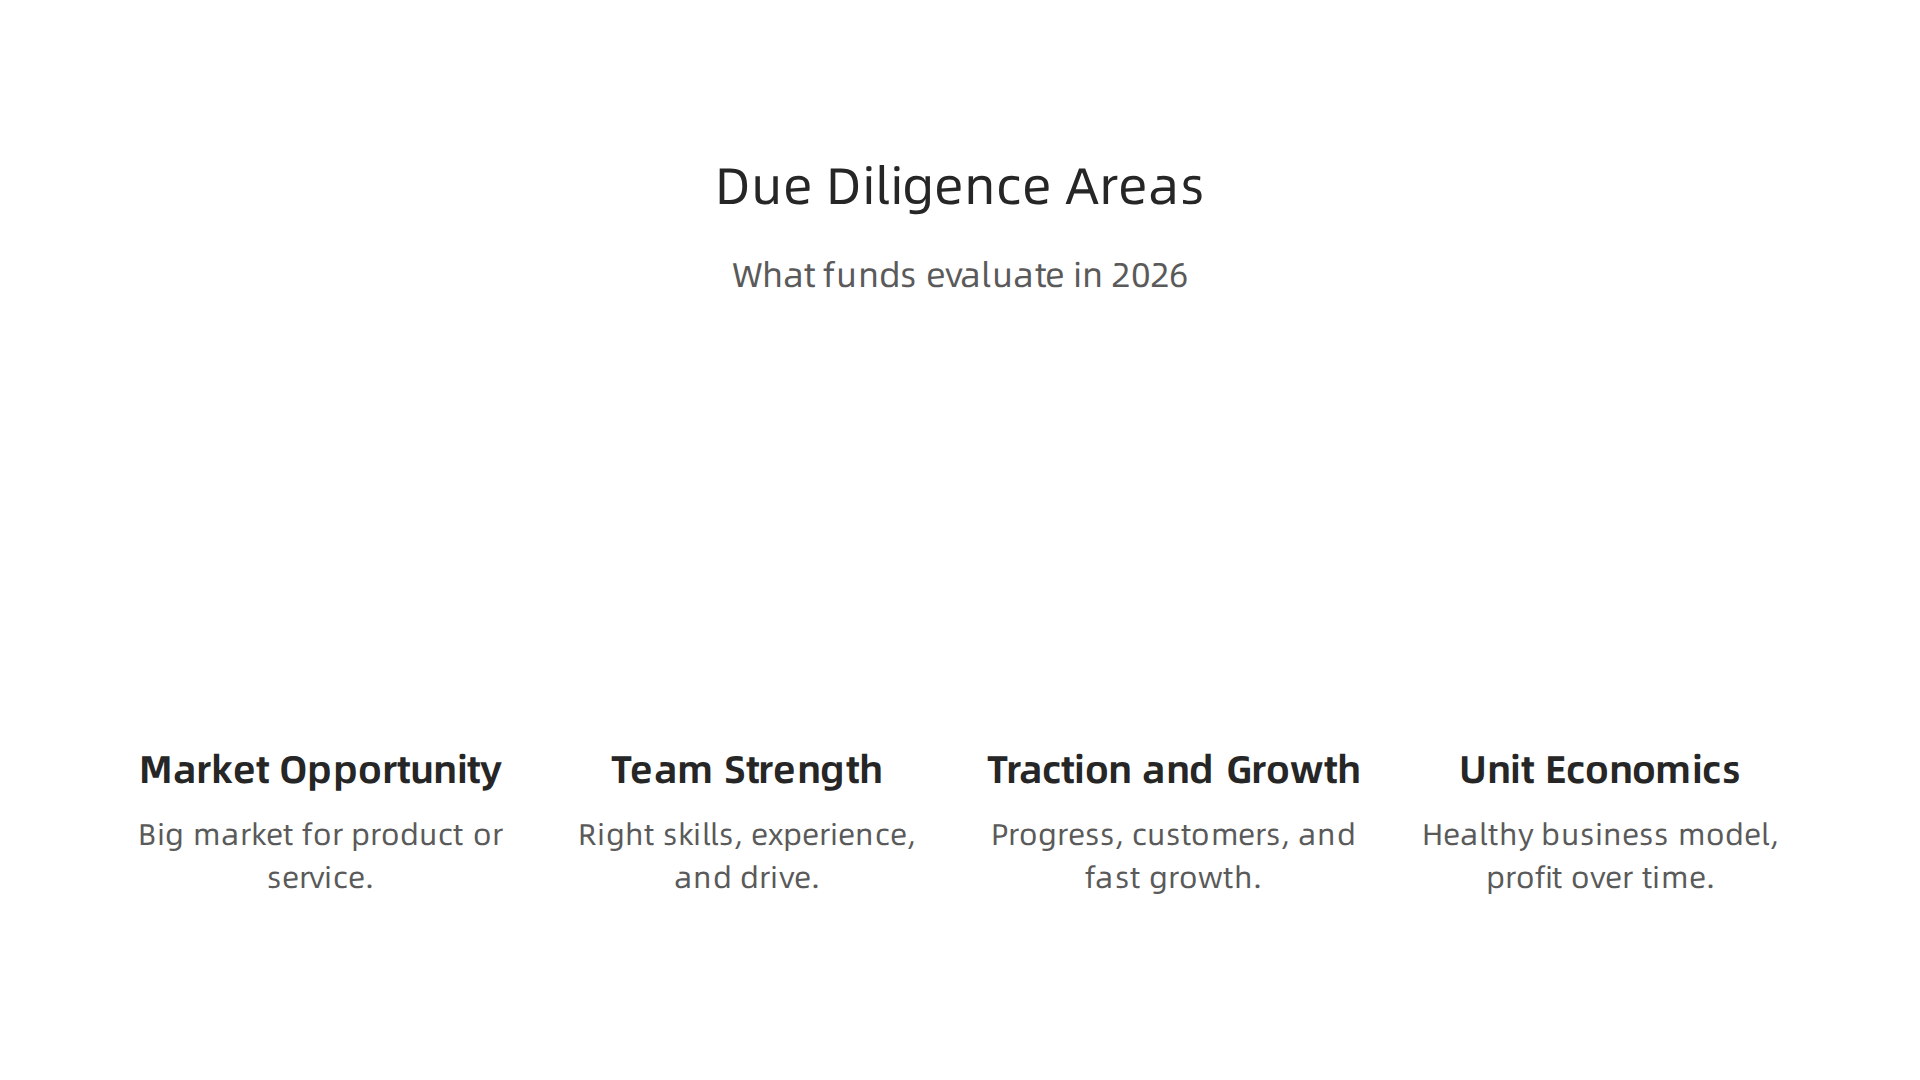
Experts say that venture capital due diligence involves looking at a startup’s money, legal standing, market, and team to find both risks and chances for growth Venture capital due diligence best practices.
Here are the main things they look at:
- Market Opportunity: Is the market for your product or service big enough? Funds want to see that many people or businesses need what you offer. They also check if your idea can really change that market. A big market means a bigger chance for them to make a lot of money.
- Team Strength: Who are the people behind the company? Investors look closely at the founders and key team members. They want to know if your team has the right skills, experience, and drive to make the company succeed. A strong team is often seen as a key signal that a startup is fundable What Signals Make Startups Fundable to VCs?.
- Traction and Growth: What progress have you made so far? This includes things like how many customers you have, how much money you are making, and how fast you are growing. Funds want to see proof that your product is working and that people like it. They look for repeatable growth and healthy business numbers How Venture Capital Investors Evaluate Early-Stage Startups.
- Unit Economics: This is about how much money you make from each customer compared to how much it costs to get them. Funds want to see that your business model is healthy. For example, if it costs you $10 to get a customer, but that customer brings in $100 over time, those are good unit economics. This shows the business can make a profit over time.
Term-Sheet Priorities: What Investors Care About
After due diligence, if a fund wants to invest, they will offer you a "term sheet." This is a document that lists the main rules of their investment. Think of it as a first draft of the deal. The terms in this sheet show what’s most important to the fund. Knowing these terms can help you in your fundraising journey. If you want to dive deeper into securing your initial capital, consider reading our guide on the founders’ guide to securing startup capital in 2026.
Some important clauses reflecting fund priorities include:
- Pro-Rata Rights: This means the fund has the right to keep its ownership percentage in your company even in future funding rounds. If you raise more money later, the fund can put in more money to avoid owning a smaller slice of your company. This shows they believe in your long-term success.
- Liquidation Preferences: This is a big one for investors. It explains how much money the fund gets back if your company is sold or goes out of business. Often, it means the investors get their initial money back (or a multiple of it) before anyone else, including the founders, gets paid. This protects their investment. More details on these terms can be found in a VC Term Sheet Explained: Key Provisions Every Founder Needs.
- Governance and Control: Funds often ask for a seat on your company’s board of directors. This gives them a say in big decisions, like hiring key people or setting the company’s direction. They do this to protect their investment and help guide your company towards a successful exit. They might also ask for certain "veto rights," meaning you can’t make specific important decisions without their approval.
By understanding how funds like venture capital firms evaluate startups and what they prioritize in a term sheet, you can better prepare your company. This knowledge helps you attract the right investors and negotiate terms that work for both sides. It’s about more than just getting working capital funding; it’s about setting up a strong partnership for growth.
Reading a Term Sheet: Clauses founders must never gloss over
The term sheet is more than just an offer; it is a map for how a fund will interact with your company for years. While we talked about liquidation preferences before, there are other important clauses that founders must understand deeply. These terms shape your control, your future earnings, and how much money you keep. An expert guide for 2026 suggests that founders really dig into these documents NVCA Term Sheet: A Founder’s Guide for 2026.
Here are some key parts of a term sheet you should pay close attention to:
- Anti-Dilution Provisions: This clause protects the investor if your company raises money later at a lower price per share. If this happens, their shares might be adjusted to keep their investment value. For founders, this means the investor gets a bigger piece of the company without putting in more money, which can reduce your own share.
- Vesting: This explains how founders earn their shares over time. Usually, you don’t own all your stock from day one. Instead, it "vests" bit by bit over a few years, like four years with a one-year "cliff." This means you need to stay with the company for a certain time to fully own your shares. If you leave early, you might lose unvested shares. This is important for securing your personal start-up capital over the long run.
- Protective Provisions: These are special rights for investors that stop you from making big decisions without their approval. This could include selling the company, taking on new debt, or changing the business plan. While they help protect the fund’s investment, too many protective provisions can limit a founder’s ability to run the company freely.
- Warranties and Representations: These are promises you make about your company being true and correct (like your financial records and legal standing). Breaking these promises can have serious consequences.
As a founder, when you review a term sheet, think about this:
- Your Control: How much say will you still have in running your company?
- Future Funding: How might these terms affect your ability to raise more working capital funding later on?
- Your Equity: How will these terms impact your ownership percentage over time?
Understanding these details is critical. If you’re looking for more ways to learn about attracting investors and managing funding, you might want to learn how to get venture capital funding for your startup in 2026. This knowledge helps you get the best deal for your company, ensuring it thrives with the right kind of support.
Stay informed about the fast-moving world of tech and investment.
Get clear daily AI updates from The AI Newsletter Worth Reading.
After understanding the tricky parts of a term sheet, it’s also key to know about the different ways founders can get money. These are called funding instruments. Each one has its own rules and changes how your company’s ownership looks, how much say you have, and how you get more money later. Let’s look at some common ways to get start-up capital.
SAFEs (Simple Agreement for Future Equity)
A SAFE is like a ticket for future company ownership. It’s a deal where an investor gives you money now, and they get company shares later, usually when you raise a bigger round of funding.
- Pros: SAFEs are pretty simple and quick to set up. They don’t have interest rates or a date when you have to pay the money back, unlike a loan. This means less stress about repaying debt early on.
- Cons: Because the company’s value isn’t set yet, you won’t know exactly how much of your company the investor will own until a later funding round. This can make it hard to see your true ownership right away. According to experts, SAFEs are not debt and do not have interest or a maturity date SAFEs vs Convertible Notes.
Convertible Notes
A convertible note is a bit different. It starts as a loan from an investor to your company. But it’s special because this loan is meant to turn into company shares later.
- Pros: Convertible notes often come with an interest rate, so investors get a bit more for their money. They also have a clear end date (maturity date) by which they either need to be paid back or convert into shares.
- Cons: Since it’s a loan, you might have to pay it back if your company doesn’t raise another funding round by the maturity date. This can add pressure. A key difference is that convertible notes are actual debt, while SAFEs are not Convertible Note Vs. SAFE: How Startup Funding Works.
Both SAFEs and convertible notes help you delay setting a firm price for your company until it grows more. This can be great for early working capital funding.
Priced Equity Rounds
This is what most people think of when they hear about companies raising money. In a priced equity round, your company’s value is set, and investors buy shares at that agreed price.
- Pros: Everyone knows exactly what their share of the company is worth. Investors become owners right away, which shows a strong commitment. This is a common way to attract venture capital.
- Cons: These rounds are much more complex and cost more money to set up, usually needing a lot of legal work. They also mean that your ownership (equity) gets smaller right away, as new shares are given to investors.
Venture Debt
Venture debt is a loan given to startups that already have some investor funding. It’s not like a regular bank loan; it’s made for growing tech companies.
- Pros: It lets you get more working capital funding without giving away more of your company’s ownership. This means less dilution of your shares. It can also help your current funds last longer.
- Cons: Like any loan, it must be paid back, usually with interest. It might also come with certain rules (called covenants) that limit what your company can do. Comparing options like SAFEs, convertible notes, and venture debt can help founders find the right financing for their needs Comparing SAFE notes, Venture Debt, and Convertible ….
Choosing how fund your company impacts everything from your ownership percentage to your control. As a founder, understanding these choices is crucial for securing smart capital solutions for every startup funding stage. Each instrument changes your cap table, your level of control, and your ability to raise more money in the future. Knowing how these work helps you make the best decisions for your company’s growth.
Choosing the right way to get money for your company is just one part of the puzzle. You also need to know who you’re asking for money. Different kinds of investors look for different things and focus on companies at various stages of growth. Knowing this helps you target the right groups, making your search for start-up capital much smarter. This is all about understanding your fundraising strategy.
Different Types of Funds and What They Look For
Not all money pots are the same. Here’s a simple breakdown of the main types of investors and what they typically want:
- Seed-Stage Funds: These funds give money to very new companies, often when you just have an idea or a very early product. They help you get started. In 2026, many funds are focused on this stage, with a good number of commitments going to funds seeking less than $15 million. The median size for a venture fund fell to $15.3 million in the first quarter of 2026, meaning many are set up for these smaller, early bets Venture Monitor. A typical first check from a seed fund might be between $500,000 and $1 million VC & Startup Benchmarks (2026).
- Early-Stage Funds (Series A, B): These investors come in when your company has shown some growth. You likely have customers, some money coming in, and a team. They want to help you grow faster. For example, in May 2026, the average deal for early-stage companies was around $4.5 million, with Series A deals hitting about $29.4 million on average The AlleyWatch May 2026 US Venture Capital Funding …. They’re looking for signs that your business can really take off.
- Growth Funds (Late-Stage): These funds put in much larger amounts of capital wholesale into bigger, more established companies. These companies usually have a proven product, lots of customers, and a clear path to becoming very successful. Growth funds help them get even bigger or prepare to go public.
- Corporate VCs (CVCs): These are investment arms of big companies. For example, Google or Microsoft might have their own venture capital groups. They invest in startups that fit with their own business goals, often looking for new technologies or markets. This kind of investment can be a powerful way to secure funding and strategic partners. To learn more about how they operate, check out our guide on corporate venture capital is the new power broker in startup funding.
- Micro-VCs: These are smaller venture capital firms. They usually have smaller funds to invest and write smaller checks, often focusing on seed-stage or very early-stage companies. They can be a great first step for founders looking for initial working capital funding.
Why Targeting the Right Fund Matters
It’s super important to know which kind of fund you should approach. If your company is just starting out, asking a growth fund for $50 million will likely be a waste of time. They aren’t set up to invest at your stage.
Instead, focusing on seed-stage or micro-VCs makes more sense. Research shows that funds focusing on seed-stage investing were 1.3 times more likely to close successfully in 2026, capturing around 70% of investor commitments Emerging Manager Performance Data Unpacked. This means there’s a lot of money actively looking for early companies.
When you understand how fund types match your company’s stage, you can craft pitches that speak directly to what those investors care about. This saves you time and makes your fundraising efforts much more effective, increasing your chances to attract venture capital funds for startup growth in 2026. It also helps you master startup investing and fundraising 2026 strategies for unrivaled success.
Staying on top of the latest trends in technology and investment can give you a real edge.
Get clear daily AI updates from The AI Newsletter Worth Reading.
Understanding the different types of investors is a good start. But after you find the right ones, you need to know how to seal the deal and work with them. This means getting smart about negotiating the agreement, understanding who owns what in your company, and building strong relationships for the long run.
Practical Tactics: Negotiation, Cap Table Modeling, and Post-Investment Relationships
Once an investor shows interest in putting their money into your company, they will offer a "term sheet." Think of this as a draft agreement that spells out the main points of the investment. Learning how fund agreements are structured and what to look for is very important.
Getting the Deal Right: Negotiating Term Sheets
Negotiating your term sheet is a key step. You might hear about things like SAFE notes and convertible notes, especially for early start-up capital.
- SAFE notes (Simple Agreement for Future Equity) are not considered debt. They are simply a promise for future stock in your company. They don’t have interest or a set date when they need to be paid back or converted SAFE vs. Convertible note vs. Priced Equity Round.
- Convertible notes, on the other hand, are a type of loan. They collect interest and usually have a date by which they must be repaid or changed into company stock SAFE Versus Convertible Note: A Founder’s Decision Guide.
It’s super important for founders to really understand the differences between these types of agreements. This knowledge helps you choose the right path for your company’s working capital funding and protect your future ownership SAFE vs. Convertible Note: A Founder’s Guide to Fundraising.
Understanding Your Company’s Ownership: Cap Table Modeling
A "cap table" is like a map that shows who owns how much of your company. It lists all the owners, like founders, employees, and investors, and how many shares they have. Before you sign any deal, you must model out different scenarios to see how new money changes this map. This is known as cap table modeling.
Why is this important? Because when investors put in money, your share of the company often gets smaller. This is called dilution. You want to make sure you’re not giving away too much too soon. Experts suggest you should model at least three different scenarios before talking to investors, including one that favors you more Cap Table for Startups – The Founder’s Complete Guide [2026].
A good rule of thumb in 2026 is to aim for giving up about 15% to 25% of your company in each funding round, especially for seed and Series A investments Cap Table Guide for Founders: Dilution Made Simple. To keep founders motivated, it’s also common for their ownership to "vest" over time, typically over four years with a one-year "cliff" How to Model Equity Ownership and Dilution Founders. This means you earn your full ownership stake over a few years, which helps protect the company if a founder leaves early. Building a clear plan for your company’s money helps you create your winning funding package for startup success.
Building Strong Investor Relationships
Getting money from investors is not the end of the journey; it’s just the start of a new relationship. Keeping your investors happy and informed is key to future success. You want them to be your partners, not just people who gave you money.
Best practices for working with investors after they’ve put in their capital include:
- Regular Updates: Send out quick updates every month.
- Meetings: Have board meetings every three months.
- Be Honest: Share both good news and bad news early. If something goes wrong, tell them what happened and how you plan to fix it Investor Relations: Managing Board and Updates Post-Funding.
Being open and honest builds trust. It shows your investors that you are a reliable leader, which makes them more likely to support you in the future. This kind of ongoing partnership helps you to attract and partner with investors in businesses for startup growth.
Summary
This article explains how investment funds work and why founders must understand fund structures, economics, and timelines to raise smart start-up capital. It covers the roles of Limited Partners (LPs) and General Partners (GPs), how funds earn money (management fees, carry, hurdle rates), and how fund life stages shape investor behavior and exit pressure. You’ll learn what investors look for in due diligence, which term-sheet clauses—like liquidation preferences, anti-dilution, and vesting—most affect founders, and the differences between SAFEs, convertible notes, priced equity rounds, and venture debt. The guide shows how to target the right type of fund for your stage, model cap table dilution across scenarios, negotiate better terms, and build strong post-investment relationships so you protect ownership and align expectations for future growth.